
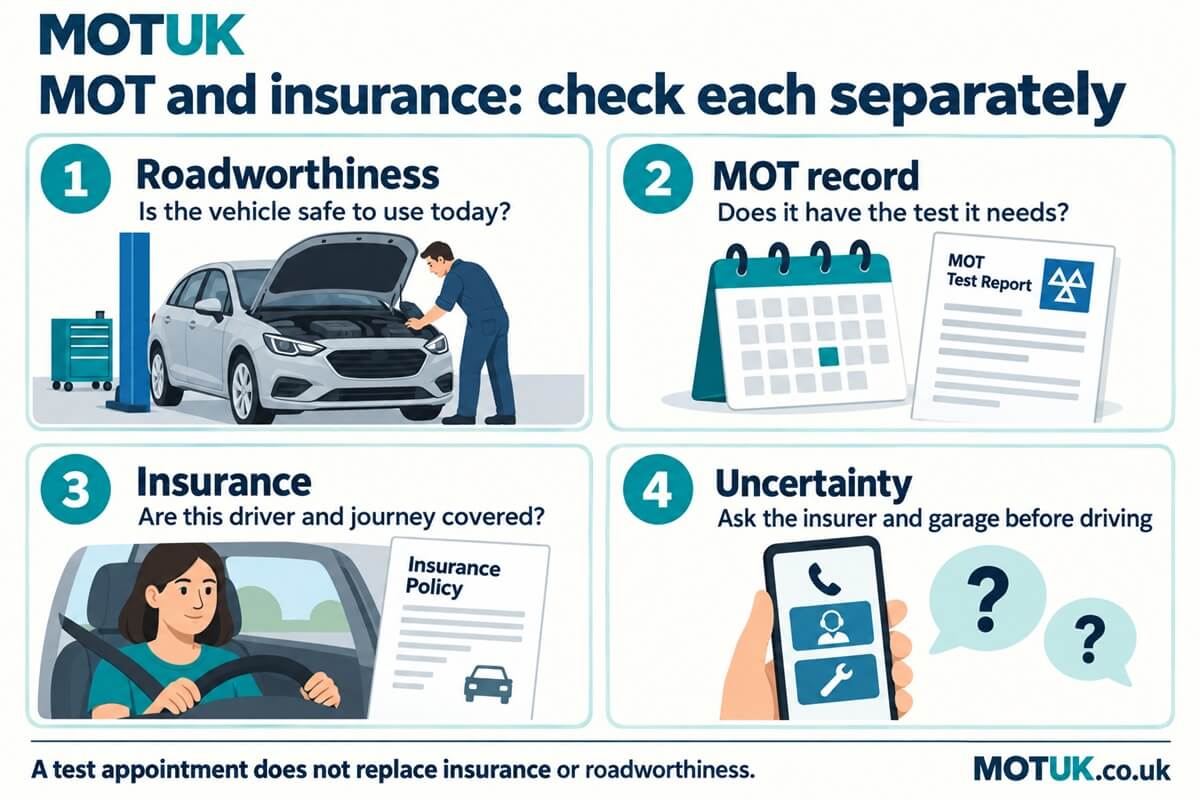
An MOT and car insurance serve different purposes. The MOT checks specified vehicle standards at the test; insurance provides the cover described in your policy. Neither replaces the other, and both need attention before you drive.
Does an expired MOT automatically cancel insurance?
It is too simplistic to say that every policy becomes void the moment an MOT expires. The wording, the vehicle’s condition and the circumstances of a claim matter. A missing certificate may still breach policy conditions and create a dispute, so do not treat uncertainty as permission to drive.
The Financial Ombudsman considers complaints about roadworthiness and claims, including whether a vehicle’s condition contributed to a loss. Its published guidance also discusses how a missing MOT can affect a write-off valuation. Ask your insurer to confirm your own cover and any requirements in writing.
Keep three separate questions in mind
- Is the vehicle roadworthy? A valid certificate does not excuse unsafe tyres, brakes or other defects that develop later.
- Does it have the MOT it needs? Check the official expiry record and arrange testing in time.
- Are this driver and this journey insured? Check permitted drivers, use of the vehicle and any relevant conditions.
Driving to an MOT or repair appointment
A pre-arranged test can fall within a limited exception to the normal MOT requirement. It does not remove the need for insurance or make a dangerous vehicle safe to drive. Tell the insurer if you are unsure whether the proposed journey is covered. If the car cannot be moved safely and lawfully, arrange recovery.
What if the vehicle fails?
Read the defect categories before leaving the centre. You must not drive with a dangerous defect. For other failures, an unexpired old certificate is only part of the picture: the vehicle must also be roadworthy. See our failed MOT guide.
A useful paperwork routine
Keep your policy schedule, MOT expiry date, service records and repair invoices together. Set separate renewal reminders and tell the insurer accurately about changes it asks you to report. If a claim is declined, request the reason and the policy clause relied on, use the insurer’s complaints process and consider the Financial Ombudsman if the dispute remains unresolved.
Reviewed 10 October 2026. MOT guidance applies to England, Scotland and Wales unless stated otherwise.